Sub-Total: $0.00
Tax Lien Investing Strategy: How It Works, Risks, and Due Diligence
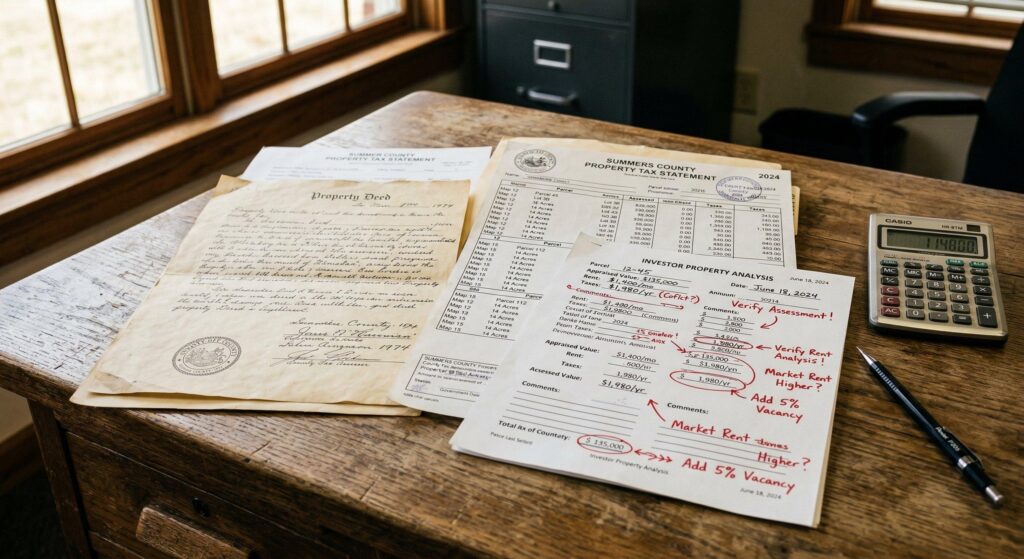
Tax lien investing is a real estate-related investment strategy that involves purchasing certain claims associated with unpaid property taxes. Depending on the jurisdiction, an investor may earn interest when a property owner redeems the tax lien. If the lien remains unpaid, additional legal steps may provide a path toward foreclosure or another remedy allowed by law.
However, tax lien investing is not the same as buying a rental property, and it does not guarantee ownership, a specific return, or a profit. State and local laws determine how tax sales work, what investors can earn, how long redemption periods last, and what must happen before an investor can pursue further legal action.
For anyone researching a tax lien investing strategy, the best starting point is understanding the rules, researching the underlying property, and establishing a disciplined bidding process before committing capital.
In this guide, we’ll cover how tax lien investing works, how to research potential opportunities, what to evaluate before bidding, and which risks beginners should understand.
My Experience Researching Tax Lien Auctions
My interest in tax lien and tax deed investing began after I encountered educational material promoting the possibility of acquiring real estate through delinquent tax sales.
The concept caught my attention. I wanted to understand how these sales worked, what rights an investor actually received, and how the process differed from purchasing a property through a traditional real estate transaction.
I spent approximately a year learning about the process and seeking answers from someone familiar with this type of investing. That research led me to examine auction lists, parcel identification numbers, public records, title information, geographic information system (GIS) maps, and the practical considerations involved in deciding whether a property warranted further investigation.
One of my early lessons came before I had even placed a bid: I attended an auction but discovered that I had missed the registration deadline. I had researched properties and prepared a list, yet I was not eligible to participate.
That experience reinforced an important point: successful preparation involves more than finding an appealing property on an auction list. Investors must understand the registration process, payment requirements, deadlines, and legal rules before auction day.
The research methods discussed below are educational guidelines. My experience should not be interpreted as a guarantee that another investor will achieve the same results.
What Is Tax Lien Investing?
A property tax lien generally represents a legal claim associated with unpaid property taxes. When property taxes remain delinquent, a taxing authority may use a process established by state and local law to collect the debt.
In jurisdictions that sell tax lien certificates, eligible investors may be able to purchase a certificate representing the tax debt and associated amounts recognized under the applicable rules.
The investor does not ordinarily become the immediate owner of the property simply by purchasing a tax lien certificate.
Instead, the certificate provides specific rights under the governing law. If the property owner redeems the lien, the investor may receive the eligible principal, interest, and other permitted amounts. If the lien is not redeemed, the investor may be able to pursue additional legal remedies, subject to statutory requirements and deadlines.
The details matter because tax lien investing differs substantially between jurisdictions.
Before pursuing an opportunity, confirm the following:
- Whether the jurisdiction sells tax lien certificates, tax deeds, or another type of tax-sale interest.
- How the auction determines the winning bid.
- What interest, penalties, or fees may legally be collected.
- How long the redemption period lasts, if one applies.
- What notices, payments, filings, and legal proceedings are required.
- What rights the investor receives if the property owner does not redeem.
Always obtain the current rules from the responsible county, municipality, tax authority, or other official agency.
Tax Liens vs. Tax Deeds: Understand the Difference
Tax lien and tax deed investing are related, but they are not interchangeable strategies.
Tax lien certificate investing
In a tax lien system, the investor purchases a qualifying claim related to delinquent property taxes. The potential outcome may involve repayment with interest or, where permitted and after following the required legal process, further action involving the property.
The investor must evaluate the certificate’s terms, redemption rules, applicable deadlines, and the underlying property’s characteristics.
Tax deed investing
In a tax deed system, the tax-sale process may involve bidding on the property itself or an interest that can result in ownership under the applicable law. The investor must still understand title requirements, redemption rights, court procedures, occupancy issues, and other restrictions that may affect the purchase.
Some jurisdictions use hybrid systems, so investors should not assume that every state follows one uniform process.
Why the distinction matters: A tax lien certificate should not be valued as if it were already a deed to a property. Likewise, a tax deed auction should not be evaluated using the same assumptions as an investment in a lien certificate.
If you’re comparing these approaches, start by reviewing the relevant jurisdiction’s official tax-sale rules and then evaluate the legal rights and costs associated with the specific opportunity.
How a Tax Lien Investing Strategy Works
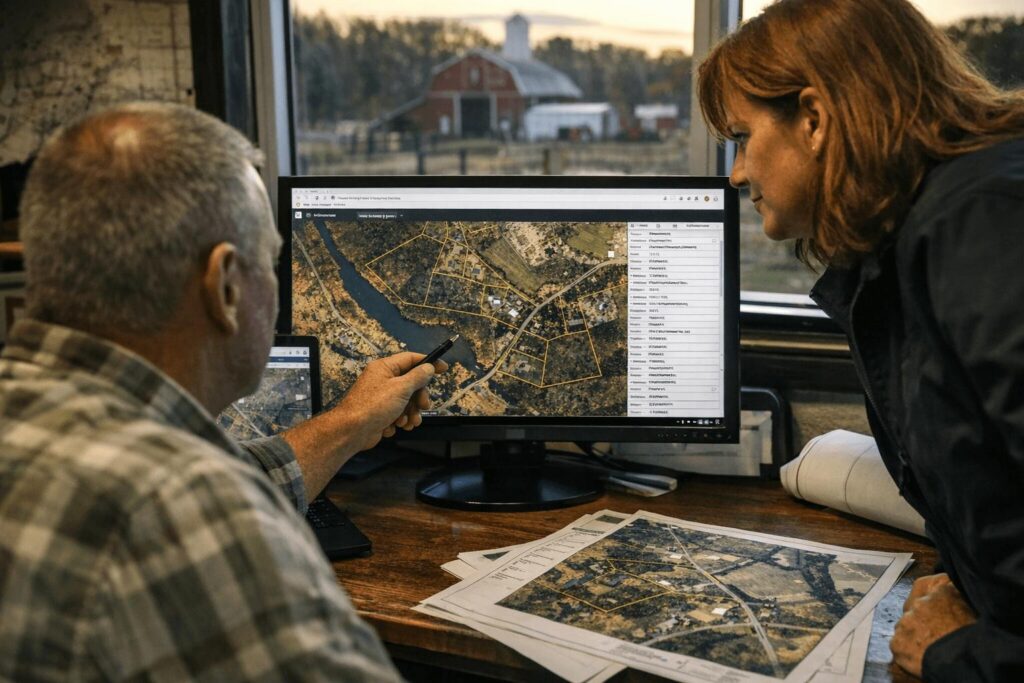
Although the details vary, a typical tax lien certificate process may involve the following stages.
Step 1: Property taxes become delinquent
A property owner does not pay property taxes by the applicable deadline. After the required notices and statutory procedures, the taxing authority may begin collection or tax-sale proceedings.
The exact timeline depends on local law. Delinquency does not automatically mean that a property will be offered to investors.
Step 2: The taxing authority identifies eligible tax-sale interests
The responsible agency identifies properties or tax claims eligible for the applicable sale process. The information may be published through an official website, a public notice, an auction portal, or another authorized method.
Listings may identify properties using a parcel identification number (PIN), assessor’s parcel number (APN), legal description, address, or other record identifier.
Do not assume every listed parcel is a suitable investment. An auction listing is a starting point for research, not a substitute for due diligence.
Step 3: Investors research the opportunity
Before bidding, investors should review the official sale documents and investigate the property or claim.
Research may include public property records, assessed information, available comparable sales, parcel boundaries, legal access, zoning, occupancy indicators, title records, and potential repair or remediation concerns.
The appropriate research depends on whether the auction concerns a lien certificate or the property itself.
Step 4: Investors register and participate in the auction
Many tax sales have registration requirements, deposits, identity verification, payment deadlines, or other eligibility conditions.
Review the official auction terms before the registration deadline. Confirm accepted payment methods, required deposits, bidding increments, premium rules, and any consequences for failing to complete a purchase.
An attractive opportunity is not useful if you cannot meet the participation requirements.
Step 5: The winning bidder completes the required payment and documentation
If you win, follow the auction administrator’s instructions exactly. Payment deadlines and documentation requirements may be strict.
Retain the sale terms, receipts, certificate or deed documents, correspondence, and any instructions concerning redemption or subsequent legal action.
Step 6: The investment follows the applicable legal process
If the property owner redeems a lien, the investor may receive the amounts allowed under the applicable rules. The timing and calculation depend on the jurisdiction and the certificate’s terms.
If redemption does not occur, the investor must not assume the property automatically becomes theirs. Additional notices, deadlines, legal proceedings, payments, or other requirements may apply.
Before bidding, understand the process for both possible outcomes and the costs associated with each.
How to Research Tax Sale Properties Before Bidding
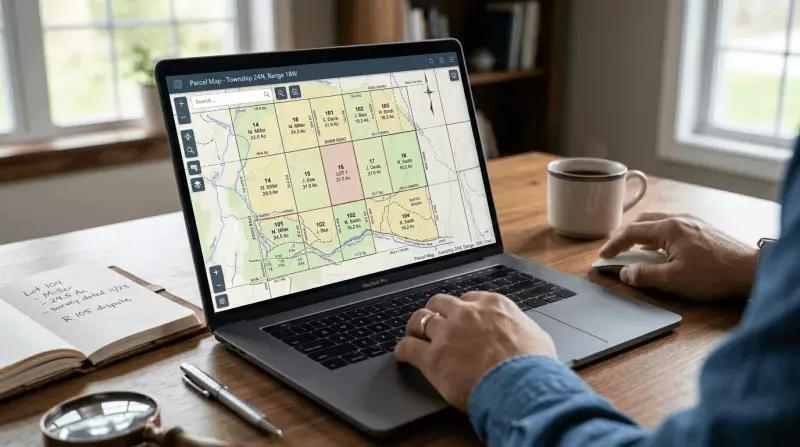
Research is one of the most important parts of a tax lien investing strategy. A low opening bid does not establish that a property is valuable, accessible, developable, or profitable.
1. Obtain the official auction list
Begin with the responsible tax collector, county treasurer, county tax claim office, court, municipality, or other agency that administers the sale.
Use third-party auction websites as discovery tools when appropriate, but verify the sale, parcel, deadline, and rules through the official source.
2. Confirm the parcel identification number
Record the parcel number and legal description for each opportunity you consider. Compare these details across the auction list, assessor’s records, GIS mapping tools, and recorded documents.
Do not rely on a street address alone. A parcel may have an incomplete address, multiple associated lots, or a legal description that differs from what appears in a listing.
3. Review parcel boundaries and legal access
Use the local GIS or parcel-mapping system to examine the parcel’s approximate location, shape, dimensions, neighboring properties, and relationship to roads.
Determine whether legal access is documented rather than assuming that a visible driveway or nearby road establishes an access right.
Some properties consist of multiple parcels. Confirm which parcels are actually included in the sale and whether the property of interest depends on an adjoining parcel for access or practical use.
GIS maps are helpful screening tools, but they are not necessarily surveys and should not be treated as definitive boundary determinations.
4. Investigate title records and other potential claims
Review available recorded documents and seek a qualified title professional or real estate attorney when appropriate.
Research may include mortgages, judgments, municipal claims, easements, restrictions, federal tax liens, bankruptcy-related issues, and other interests that could affect the investment.
The effect of each claim depends on the applicable law and the specific sale process. Do not assume that a tax sale eliminates every lien, interest, or title problem.
5. Evaluate zoning and permitted use
Check the local zoning code and other applicable land-use requirements. A parcel’s location or appearance does not guarantee that it can be developed, expanded, subdivided, or used for a particular purpose.
Confirm relevant setbacks, permitted uses, environmental restrictions, flood concerns, utility availability, and any required approvals when these factors could affect the property’s intended use.
6. Review physical condition and occupancy
When legally and practically possible, inspect the property from an authorized location and review reliable available information about its condition.
A drive-by or aerial image may reveal obvious concerns, but it cannot confirm the condition of a roof, foundation, electrical system, plumbing, interior, or other hidden components.
Also consider whether the property appears occupied. If ownership or possession is later obtained, occupants and possession-related legal requirements can affect the timeline and cost of the investment.
Never enter private property without proper authorization.
7. Estimate market value and realistic costs
For a potential property acquisition, review comparable sales, local demand, property condition, and the likely costs of bringing the property to its intended use.
Potential costs may include legal fees, title work, taxes, recording fees, repairs, cleanup, insurance, utilities, financing, and the cost of resolving title or occupancy issues.
For a lien certificate, analyze the certificate’s legal terms and potential repayment outcomes separately from the underlying property’s market value. Property value alone does not determine the certificate’s yield or the likelihood of repayment.
How to Establish a Maximum Bid
Set your maximum bid before the auction starts. This helps prevent competitive bidding from replacing disciplined investment analysis.
For a tax lien certificate, evaluate the amount invested, permitted interest calculation, expected holding period, auction format, redemption rules, and the cost of pursuing any additional remedies. Consider how your capital would be tied up if the expected outcome takes longer than planned.
For a tax deed or other direct property acquisition, estimate the property’s realistic value and subtract the costs and risks associated with the intended exit strategy.
A simplified property acquisition framework is:
Maximum acquisition price = conservative expected resale value − estimated project costs − required profit margin − risk contingency
This is a screening framework, not a legal or valuation formula. Adjust it for the property, jurisdiction, financing, and intended use.
For either strategy, ask:
- What is the most likely outcome?
- What happens if the timeline is longer than expected?
- How much additional capital could be required?
- What legal or administrative steps could prevent or delay the expected result?
- What other investment opportunities would be sacrificed by tying up this capital?
If the opportunity only works under an optimistic assumption, reconsider the bid.
Risks of Tax Lien Investing
Tax lien investing can involve legal, financial, administrative, and property-related risks. Understanding them before bidding is essential.
State and local rules can differ
Registration, auction mechanics, interest calculations, redemption periods, notices, deadlines, and enforcement procedures can differ significantly. Research the rules for the exact jurisdiction and sale.
The advertised rate may not be your realized return
A statutory interest rate or auction headline does not guarantee that you will earn that rate. Auction competition, the amount invested, redemption timing, allowable costs, and the actual outcome can affect realized returns.
Never evaluate a tax lien solely by comparing its advertised rate with a bank account, bond, or stock-market return.
Legal complications can increase costs
Title issues, competing claims, bankruptcy, required notices, and court proceedings can delay or complicate the process. An attorney may be necessary to understand the rights and steps involved.
The property may have significant defects
A property associated with a tax sale may have structural damage, environmental concerns, access problems, code violations, unpaid charges, or restrictions on its use.
A parcel with a low opening bid is not necessarily a bargain.
Capital may be tied up longer than expected
Redemption and legal timelines can delay the return of capital or prevent an investor from pursuing a desired outcome as quickly as anticipated.
Consider liquidity needs before committing money that may not be readily accessible.
Ownership is not guaranteed
Buying a tax lien certificate does not automatically convey ownership of the underlying property. Any later path toward ownership depends on the governing law and successful completion of the required process.
Common Mistakes Beginners Should Avoid
Before participating in a tax sale, watch for these common mistakes:
- Bidding without understanding the local rules.
- Missing registration or payment deadlines.
- Treating a tax lien certificate as if it were a deed.
- Assuming a low opening bid reflects the property’s value.
- Relying on an auction listing without independently verifying the parcel.
- Skipping title, access, zoning, and property research.
- Assuming that all existing liens or interests disappear after a sale.
- Calculating potential returns using an advertised interest rate alone.
- Ignoring legal expenses, holding costs, or the possibility of delayed recovery.
- Bidding without a written maximum bid and a clear exit plan.
The objective is not to win every auction. It is to identify opportunities whose terms, risks, and potential outcomes fit your investment criteria.
Frequently Asked Questions About Tax Lien Investing
Is tax lien investing the same as buying real estate?
No. In a tax lien certificate sale, the investor generally purchases a claim associated with delinquent property taxes rather than immediate ownership of the property. A tax deed sale may involve acquiring the property or an interest that can lead to ownership under the applicable rules.
Can you make money investing in tax liens?
An investor may receive interest or other amounts permitted under the governing law if a lien is redeemed. If it is not redeemed, further legal remedies may be available in some jurisdictions. However, returns are not guaranteed, and costs, timing, legal complications, and the terms of the sale affect the outcome.
Does a tax lien certificate automatically give you the property?
No. A certificate does not ordinarily convey immediate ownership. If the lien remains unredeemed, the investor must follow the legal process required by the jurisdiction before any ownership-related remedy can occur.
How do I find tax lien auctions?
Start with the official website or office of the county, municipality, tax collector, treasurer, or other agency responsible for the sale. Some jurisdictions also use authorized online auction platforms or publish required notices through other channels. Verify current dates, registration requirements, and sale terms directly with the responsible authority.
What should I research before bidding?
At a minimum, verify the auction rules and parcel identity, research available title and public records, examine parcel boundaries and legal access, investigate zoning and potential property concerns, and calculate the costs and risks relevant to the type of investment. Consider professional legal or title assistance when appropriate.
Is tax lien investing suitable for beginners?
Beginners can learn about the strategy, but they should not assume it is simple or low risk. Start by studying one jurisdiction’s rules, reviewing official sale documents, and practicing due diligence before committing capital. Avoid bidding until you understand the certificate or property rights being offered.
Build a More Disciplined Real Estate Investment Process
Tax lien investing is only one way to explore real estate opportunities. Whether you’re evaluating a tax sale, analyzing a rental property, or considering a renovation project, a consistent process for assessing costs, risks, and potential outcomes can help you make more informed decisions.
Explore InvestingTE’s real estate investment calculators and educational resources to support your broader property-investment analysis.
- How to Analyze a Rental Property
- How to Calculate Rental Property Cash Flow
- How to Calculate Cash-on-Cash Return
- 12 Tax Lien & Tax Deed Auction Websites
- Explore InvestingTE’s Investment Tools
Use a rental property calculator for rental-property assumptions, not as a substitute for analyzing a tax lien certificate’s legal terms or expected yield.
Educational disclaimer: This article provides general educational information and is not legal, tax, financial, title, or investment advice. Tax sale procedures and investor rights vary by jurisdiction and can change. Verify current rules with the responsible government authority and consult qualified professionals before bidding or taking legal action. Investing involves risk, and no particular outcome or return is guaranteed.
References: Internal Revenue Service — Understanding the difference between a tax lien and a levy. This helps explain the general legal meaning of a lien, though it is not a substitute for local tax-sale law.
IRS Taxpayer Advocate Service — Liens. Useful for background on federal tax liens.
FREE Deal Analysis for Rental Property Calculator!
Our mission is to help others develop using our tools and educational information.
Explore our tools, education and services.